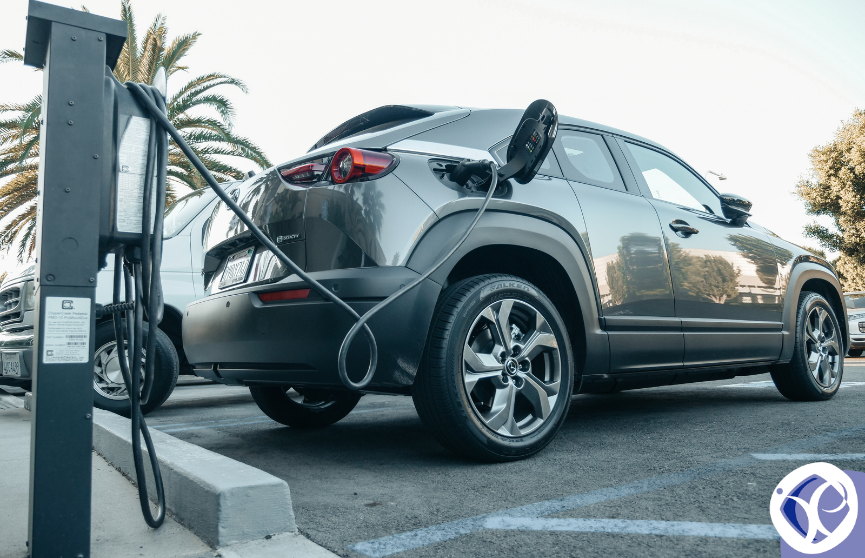
The latest Autumn Budget has brought important changes for business owners considering an electric company car. While electric vehicles continue to offer significant tax advantages over petrol and hybrid alternatives, some of these benefits are becoming less generous. With a valuable Corporation Tax allowance due to expire next year, businesses may need to act sooner rather than later.
(Reading Time: Approx. 5 minutes)
Topics Discussed:
- How first-year allowances and Benefit in Kind charges affect the cost of a £50,000 company car.
- Changes to mileage allowances, public charging VAT and the deadlines businesses should consider.
Understanding the 100% First-Year Allowance
A significant advantage of purchasing a new, fully electric car through a limited company is the 100% first-year allowance. This allows the company to deduct the qualifying cost of the vehicle from its taxable profits in the accounting period of purchase, rather than claiming relief gradually over several years.
Take a new electric vehicle costing £50,000, assuming the whole amount qualifies for capital allowances. The company can claim a £50,000 deduction. At a Corporation Tax rate of 25%, this could provide an initial tax saving of £12,500.
The 100% first-year allowance is due to end on 31st of March 2027. Following this, the allowance will only be 12%. This would instead reduce the tax saving on the same car to £1,500.
The allowance applies to new and unused zero-emission cars, not second-hand electric vehicles or plug-in hybrids. Qualifying expenditure on electric vehicle charge points can also attract a 100% first-year allowance. Businesses should therefore review their purchasing plans before that deadline.
How Benefit in Kind Tax Affects Drivers
Where a company provides a car for an employee or director’s private use, a taxable Benefit in Kind (BIK) normally arises. The calculation is based on the vehicle’s taxable list price, including relevant accessories, multiplied by a percentage determined by emissions and, for some plug-in hybrids, electric range.
To compare three hypothetical vehicles, assume each has a £50,000 taxable list price, the driver pays Income Tax at 40%, the plug-in hybrid emits no more than 50g/km and offers 40 to 69 miles of electric range, and the petrol car emits 130g/km.
The table below illustrates how the annual tax liability changes as BIK rates increase.
| Tax Year | Fully Electric EV | Plug-in Hybrid (PHEV) | Petrol Car |
|---|---|---|---|
| 2026/27 | 4% BIK, £800 tax | 10% BIK, £2,000 tax | 32% BIK, £6,400 tax |
| 2027/28 | 5% BIK, £1,000 tax | 11% BIK, £2,200 tax | 33% BIK, £6,600 tax |
| 2028/29 | 7% BIK, £1,400 tax | 18% BIK, £3,600 tax | 34% BIK, £6,800 tax |
| 2029/30 | 9% BIK, £1,800 tax | 19% BIK, £3,800 tax | 35% BIK, £7,000 tax |
| 2030/31 | 10% BIK, £2,000 tax | 20% BIK, £4,000 tax | 36% BIK, £7,200 tax |
Figures represent annual Income Tax for a 40% taxpayer on a £50,000 car, rather than the taxable benefit itself. They assume the stated emissions and electric range.
The particularly sharp hybrid increase from April 2028 reflects the move to a uniform 18% rate for cars emitting 1 to 50g/km. Although electric vehicle BIK rates are also increasing, the figures demonstrate that fully electric company cars remain considerably more tax-efficient than the alternatives.
Actual charges depend on each vehicle’s emissions, range and taxable value, while the company may also owe employer’s National Insurance on the benefit.
Changes to Business Mileage Rates
The April 2026 changes increased the approved tax-free mileage allowance for employees using their own cars or vans for business from 45p to 55p per mile for the first 10,000 miles. The rate above that threshold remained 25p. The latest Budget confirms that the higher-mileage rate will rise to 35p from 6 April 2027.
For someone driving 12,000 qualifying business miles, the approved amount is £6,000 in 2026/27, compared with £6,200 from April 2027.
For company cars, HMRC instead publishes advisory fuel and electricity rates for reimbursing business journeys. From September 2026, the fully electric advisory rates are 7p per mile for home charging and 15p for public charging, with higher substantiated actual costs potentially allowable. Hybrid company cars use the relevant petrol or diesel advisory rates.
Public Charging and the VAT Changes
The Budget also clarified the VAT treatment of public and workplace electric vehicle charging. From 1 November 2026, legislation explicitly excludes electricity supplied through public and workplace charge points from domestic electricity VAT relief. These supplies are generally subject to the standard 20% VAT rate.
Crucially, this is a confirmation of HMRC’s longstanding treatment rather than a new 20% charge being added for the first time. Electricity supplied for charging at home may qualify for domestic relief, subject to the relevant conditions. VAT-registered businesses should examine whether any charging VAT can be recovered under the usual input tax rules.
Why Timing Matters
Although company electric cars remain attractive, the combination of rising BIK rates and the approaching first-year allowance deadline should encourage business owners to review their options now. An order alone does not necessarily secure the allowance, since the timing of qualifying expenditure matters.
A separate mileage-based Electric Vehicle Excise Duty is also scheduled from April 2028, at 3p per mile for battery electric cars and 1.5p for plug-in hybrids, adding another consideration to long-term running costs.
Summary
Purchasing a new electric vehicle through a company can still deliver substantial Corporation Tax relief and lower personal tax bills than comparable petrol or plug-in hybrid cars. However, the rules are changing, and the opportunity to claim the 100% first-year allowance is currently set to end in March 2027.
Before committing to a vehicle, get in touch with us at Tax Expert. Our tax experts can review your circumstances, compare the available options and help you structure your purchase as tax-efficiently as possible.
Fill out our form here, email us at info@taxexpert.co.uk, or message us on our WhatsApp for out of office hours.
Our partnered Solicitors, Help Me Legal, have a Free Wills Month starting in October, providing an opportunity to review your arrangements and ensure you have an appropriate will in place. For more information, contact Saara at Help Me Legal on wecare@helpmelegal.uk.
Kind regards,
Ilyas Patel